For over a decade, the financial engine of B2B software looked like a fairy tale for Silicon Valley VCs and growth equity funds. You hired an SDR army, sold licenses by headcount, and let the magic of recurring revenue compound. Today, that golden playbook is showing serious wrinkles. Whether you are preparing your company for a strategic exit or scouting lower-middle-market acquisition targets, clinging to legacy SaaS valuation models is like navigating Wall Street with a 1998 Rand McNally road atlas—you are going to end up in a ditch.
The rapid adoption of generative AI and autonomous agents has blown up the social contract between software vendors and enterprise buyers. The paradox is brutal: the better your software performs thanks to AI, the fewer employees your client needs to operate it. And the fewer employees they have on payroll, the fewer user licenses they buy from you. Welcome to the era of voluntarily shrinking your own revenue base.
The end of the golden age for recurring revenue multiples
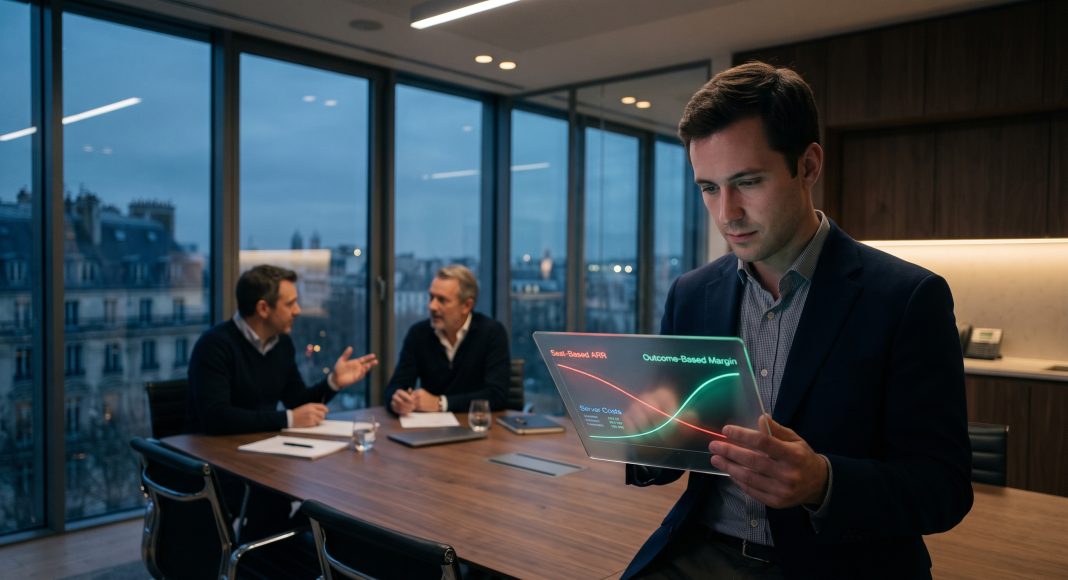
Historically, slapping a clean 3x to 5x multiple on Annual Recurring Revenue (ARR) was the comforting rule of thumb for pricing a healthy, profitable B2B software business. In 2026, that accounting reflex is the fastest way to overpay for a melting ice cube. Savvy buyers no longer take top-line ARR growth at face value without dissecting its exact underlying mechanics.
The seat-based pricing model is suffering from structural erosion. When a fifty-person customer support floor is replaced by five human supervisors orchestrating AI agents, the ticketing software vendor sees its contract value slashed by ninety percent—even as the total volume of resolved tickets skyrockets. To an acquirer, a SaaS business that still relies on human headcount for more than 60% of its revenue represents a massive medium-term churn liability. Valuation multiples for these stagnant incumbents now hover painfully below 2x ARR, assuming they find a buyer at all.
The scissor effect of inference costs on gross margins
The second shockwave rattling investment committees hits the income statement directly: the silent collapse of gross margins. The classic pure-play software dogma relied on near-zero marginal costs. Spinning up another user seat cost virtually nothing, allowing vendors to boast enviable gross margins between 80% and 85%.
Integrating Large Language Models (LLMs) has shattered that equation. Every prompt, every automated summary, and every background action triggered by an agent burns tokens and compute power. Many founders, intoxicated by the rapid adoption of their shiny new AI features, forgot to pass those inference expenses on to their pricing tiers. The result is a toxic loop: the more customers love and use the product, the higher the monthly bill from foundational model APIs climbs, quietly hollowing out profitability. A software company reporting 75% gross margins on paper that drops to 52% once API calls and GPU hosting are isolated is no longer a true SaaS—it is a disguised services business wearing an overly optimistic valuation multiple.
The new pre-acquisition audit grid: 4 criteria to avoid value traps
To avoid getting stuck with assets that look cheap on a spreadsheet but are structurally doomed (classic value traps), M&A teams now apply a ruthless filter during financial and technical due diligence. Here are the four metrics separating a high-multiple gem from a costly liability.
1. AI-adjusted gross margin
Auditors no longer stop at the top-level Cost of Goods Sold (COGS) line. They demand a granular breakdown of AI model expenditures per customer cohort and per feature. The goal is to verify whether unit economics improve or degrade as heavy usage scales. A top-tier contender in 2026 must prove it can intelligently route queries between heavyweight frontier models and lightweight Small Language Models (SLMs) to defend a true gross margin above 70%.
2. Autonomous agent resilience score
Ask yourself one simple question: if your largest enterprise client cuts its headcount by two-thirds tomorrow morning through automation, what happens to your top line? Due diligence evaluates how heavily your product relies on a human-facing user interface. Software that is merely a pretty UI wrapper sitting on top of a standard database will be bypassed entirely by autonomous agents interacting directly via API. Conversely, a platform anchored in complex proprietary workflows, exclusive data sets, and deep system integrations becomes the mission-critical infrastructure those agents must plug into.
3. Hybrid or usage-based pricing adoption ratio
A founder promising to overhaul their pricing page “right after closing” sends buyers running for the exits. M&A teams measure the exact percentage of revenue already generated by metrics decoupled from human seats: transaction volumes processed, compute credits consumed, or a share of verified cost savings. Generating at least 30% of your revenue from actual consumption or measurable outcomes proves that your customer base accepts the model and your sales reps know how to close it.
4. Usage-driven net dollar retention (NDR)
Net Dollar Retention remains king, but the way investors read it has flipped. An NDR above 110% engineered purely through aggressive price hikes on shelfware licenses is a glaring red flag. Acquirers look for organic expansion driven by workload consumption: the customer pays more because the software is doing exponentially more heavy lifting on their behalf, not because they hired three more interns.
How to shift to outcome-based pricing without triggering a customer revolt
Moving from predictable monthly subscriptions to outcome-based pricing requires surgical precision. If you abruptly tell legacy enterprise clients that their invoice will now fluctuate wildly based on the mood of your algorithms, expect immediate pushback from their procurement department.
The winning transition relies on a three-step hybrid architecture. First, establish a fixed platform fee that covers your baseline infrastructure overhead and guarantees a predictable revenue floor for your balance sheet. Second, bundle monthly allowances of action credits into each subscription tier so buyers feel protected against sudden bill shock. Third, meter overages strictly around delivered business value: a qualified sales lead nurtured end-to-end, an invoice reconciled with zero human touch, or a support ticket fully resolved. Your customer is no longer buying a productivity tool to help their staff work faster; they are buying the finished work itself.
Frequently asked questions about SaaS valuation in the AI era
Is a purely seat-based SaaS uninvestable or unsellable in 2026?
No, it can still transact, but expect a steep haircut. Turnaround private equity firms actively acquire these legacy assets at compressed multiples (often between 1.5x and 2.5x ARR) with the explicit playbook of executing the pricing migration and technical refactoring post-close.
What is the real difference between usage-based and outcome-based pricing?
Usage-based pricing meters raw technical consumption, such as API calls, tokens processed, or gigabytes stored. Outcome-based pricing charges for the successful completion of a specific business task, regardless of how much compute power it took under the hood. The latter commands the highest valuation multiples because it fully aligns vendor incentives with client ROI.
How do you reassure M&A buyers about revenue predictability when ditching fixed seats?
By locking in annual committed spend contracts. Enterprise customers commit to a minimum annual consumption budget in exchange for discounted unit rates, giving the vendor the GAAP revenue visibility banks and acquirers love while capturing upside as AI workloads scale.